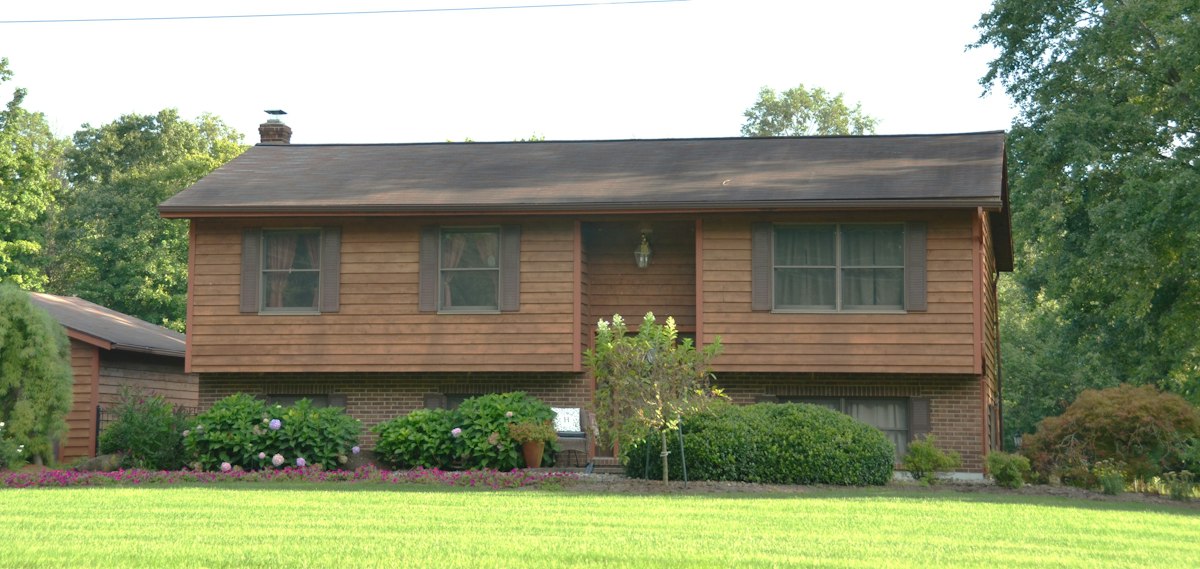
Buying A House
Deciding to acquire a residence represents one of the most significant financial and emotional milestones in an individual's life. It is a transition from the flexibility of renting to the permanence and responsibility of ownership. This transition involves more than just selecting a structure with four walls; it is about finding a sanctuary that aligns with personal values, long-term goals, and financial stability. The process is often viewed as a rite of passage, signaling a new chapter of independence and investment in one's future.
In the current economic landscape, the path to obtaining a deed is increasingly complex. Fluctuating interest rates, varying inventory levels, and evolving urban development patterns have transformed the way potential owners approach the market. It is no longer a simple matter of finding a property and signing a contract. Instead, it requires a sophisticated understanding of market trends, a deep dive into personal creditworthiness, and a strategic approach to negotiation. Preparation has become the cornerstone of a successful transaction.
Related posts
Luxury Houses for Sale
The pursuit of extraordinary real estate represents an ambition to combine personal comfort with exceptional architectural achievement. High-end...
Read more →
Luxury Homes for Sale
The realm of high-end real estate represents far more than mere shelter; it reflects a convergence of architectural...
Read more →
New Property for Sale
The modern real estate landscape offers an intriguing range of opportunities, with freshly constructed residences standing at the...
Read more →
Best Commercial Property for Lease
The world of commerce is constantly shifting, yet one fundamental element remains a cornerstone of success: the physical...
Read more →Beyond the financial implications, the psychological aspect of this endeavor cannot be overlooked. The search for a place to call home often involves a delicate balance between logical requirements—such as square footage and proximity to work—and the intangible feeling of belonging. Many prospective buyers find themselves navigating a sea of options, each with its own set of advantages and compromises. Maintaining a clear vision amidst the noise of the open market is essential for ensuring that the final choice remains a source of joy rather than a burden.
The complexity of the modern real estate environment necessitates a methodical approach. From the initial spark of interest to the final exchange of keys, every step requires careful consideration and due diligence. Understanding the legalities, the hidden costs, and the long-term maintenance requirements ensures that the investment remains sound for years to come. By treating the acquisition as both a personal dream and a professional business deal, individuals can navigate the hurdles of the industry with confidence and clarity.
As we explore the various facets of this journey, it becomes clear that success is rarely the result of luck. It is the product of research, patience, and the ability to adapt to changing circumstances. Whether one is looking for a suburban retreat, a city loft, or a rural escape, the fundamental principles of property acquisition remain the same. The following sections delve into the essential components of the process, providing a comprehensive overview of what it takes to secure a place in the competitive world of real estate.
The Financial Foundation of Property Acquisition
Before stepping foot into an open house, a thorough evaluation of one's financial standing is imperative. The ability to secure a mortgage and manage the ongoing costs of ownership depends heavily on the groundwork laid months, or even years, in advance. Lenders scrutinize every detail of a borrower's financial history, making it necessary to present a profile that demonstrates reliability and fiscal responsibility.
Assessing Credit Readiness and Debt Ratios
A primary factor in the approval process is the credit score, which serves as a reflection of past financial behavior. A higher score typically unlocks more favorable interest rates, which can save an owner tens of thousands of dollars over the life of a loan. In addition to the score, lenders evaluate the debt-to-income (DTI) ratio. This metric compares monthly debt obligations to gross monthly income. Maintaining a low DTI is crucial, as it signals to the lender that the borrower has sufficient cash flow to handle a new mortgage payment without being overextended.
Accumulating the Necessary Capital
The financial commitment extends beyond the monthly mortgage payment. Prospective owners must account for the initial down payment, which traditionally sits at twenty percent of the purchase price, though many modern programs allow for significantly less. Furthermore, closing costs—which include loan origination fees, title insurance, and government taxes—can add another three to five percent to the total cost. Establishing a dedicated savings fund specifically for these expenses prevents last-minute hurdles during the final stages of the transaction.
The Search for the Ideal Property
Once the financial parameters are established, the search for the right property begins in earnest. This phase is often the most exciting but also the most taxing, as it involves filtering through countless listings to find a match that meets both aesthetic preferences and functional needs. A disciplined approach to the search helps prevent emotional fatigue and ensures that the final decision is based on objective criteria.
Defining Lifestyle Needs and Non-Negotiables
Every prospective owner has a unique set of requirements. For some, a home office is a necessity in the era of remote work; for others, a large backyard or a specific school district takes priority. Creating a list of non-negotiable features versus "nice-to-have" amenities allows for more efficient browsing. It is also important to consider the future; a property that fits a single individual today may not accommodate a growing family or changing physical needs five or ten years down the line.
Analyzing Neighborhood Dynamics and Future Growth
A house does not exist in a vacuum; it is part of a community. Investigating the neighborhood is just as important as inspecting the structure itself. Factors such as local crime rates, the quality of public services, and the proximity to grocery stores and parks significantly impact the quality of life. Additionally, researching planned infrastructure projects or commercial developments in the area can provide insight into future property value appreciation. Buying into an improving area can lead to significant equity gains over time.
The Intricacies of the Transaction
When a suitable property is identified, the process moves into the high-stakes world of offers and inspections. This is where the deal is either solidified or falls apart. Understanding the mechanics of the contract and the importance of professional oversight is vital for protecting one's interests.
The Role of Professional Representation
Engaging a real estate agent provides a layer of expertise that is difficult to replicate independently. These professionals understand the nuances of local market pricing and can provide invaluable assistance during the negotiation phase. They act as a buffer between the buyer and the seller, ensuring that communications remain professional and focused on the terms of the deal. Furthermore, they can identify potential red flags in a listing that an untrained eye might miss.
The Inspection and Appraisal Phase
An accepted offer is usually contingent upon a satisfactory home inspection and a professional appraisal. The inspection is a comprehensive review of the property's physical condition, including the roof, plumbing, electrical systems, and foundation. Discovering structural issues at this stage allows the buyer to request repairs or a price reduction. Simultaneously, the appraisal ensures that the property's value aligns with the purchase price, which is a requirement for most lenders. These steps serve as essential safeguards against overpaying or inheriting a money pit.
Closing the Deal Successfully
The final stage of the journey is the closing, often referred to as settlement. This involves a mountain of paperwork where the title is officially transferred from the seller to the buyer. It is the culmination of all the research, saving, and negotiating. Before the final signatures are placed, a final walkthrough is conducted to ensure the property is in the agreed-upon condition and that no new issues have arisen since the inspection. Once the funds are disbursed and the deed is recorded, the transition to homeownership is complete, marking the beginning of a new chapter in a personalized space.
Conclusion
The process of buying a house is a multifaceted endeavor that requires a blend of financial discipline, market savvy, and emotional resilience. While the path may be filled with complexities, the reward of owning a piece of real estate provides a sense of security and a foundation for building long-term wealth. By focusing on thorough preparation and maintaining a clear perspective throughout the search and negotiation phases, individuals can successfully navigate the market and secure a home that serves their needs for many years to come.